
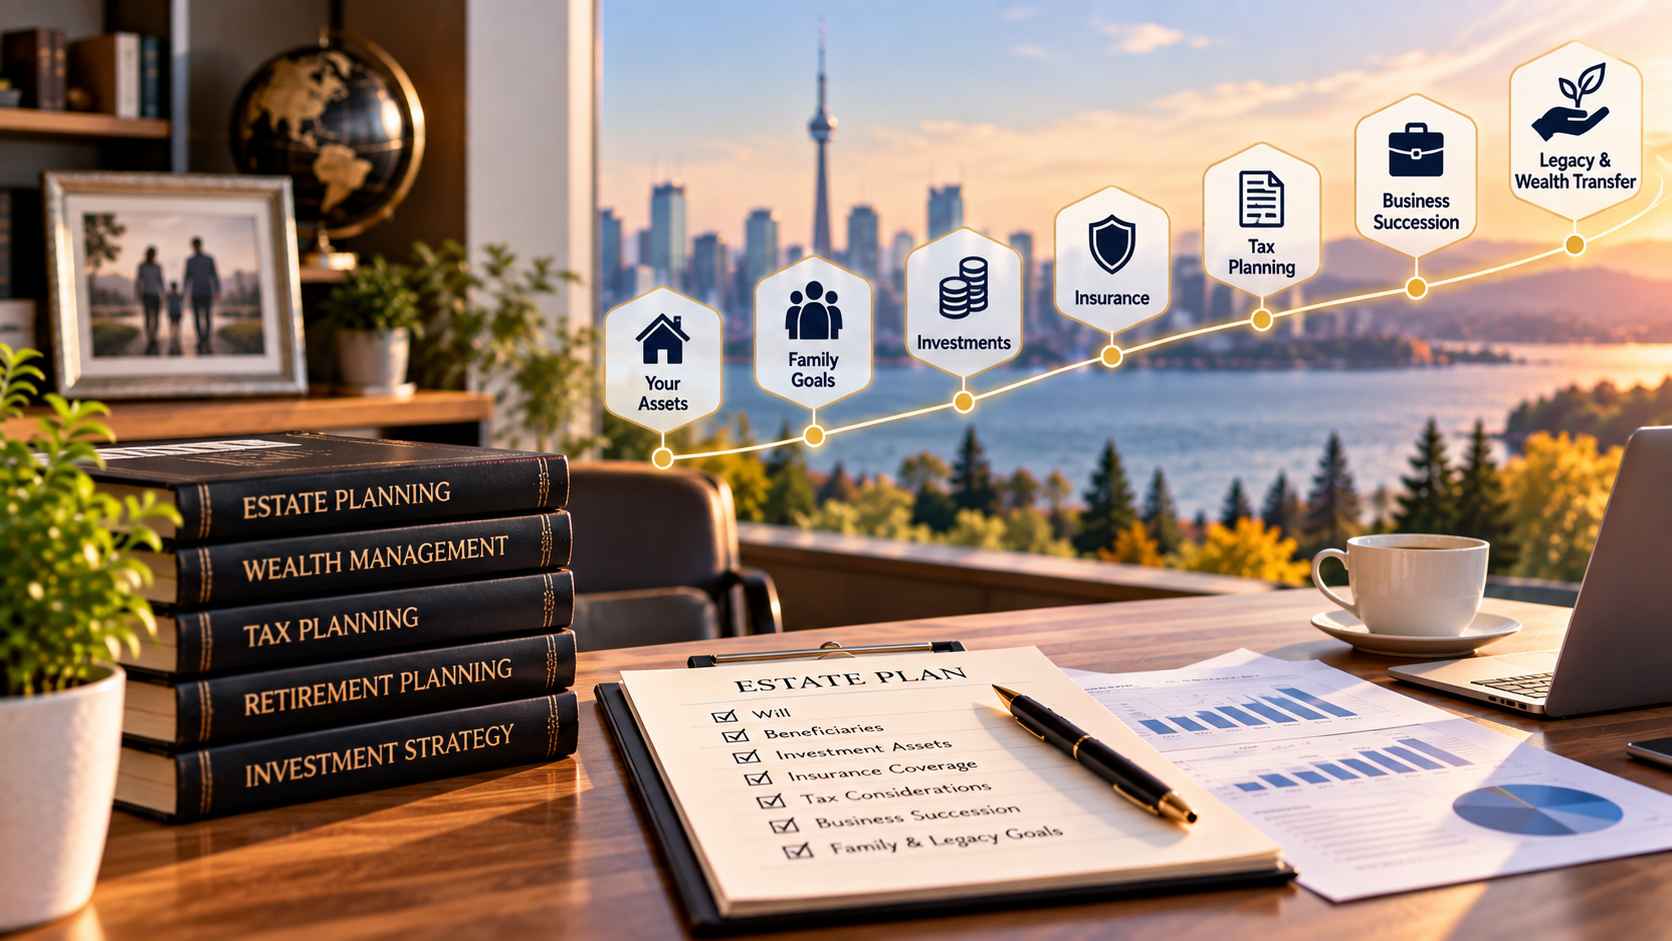
Estate planning is often associated with writing a will, naming beneficiaries, and deciding who should receive assets. Those are important elements, but a well-considered estate plan can involve much more.
For individuals and families with investments, insurance, real estate, business interests, or significant accumulated wealth, estate planning intersects with retirement planning, taxation, investment management, family priorities, and wealth transfer.
That is why estate planning can be more useful when viewed as part of a broader financial strategy rather than as an isolated legal document.
Estate Planning Is More Than a Will
A will is an important part of an estate plan because it can communicate how a person’s estate should be handled after death. It can also identify an executor who will be responsible for administering the estate.
However, not every asset necessarily passes through a will in the same way.
Beneficiary designations on certain financial products and insurance policies can have an important role. Joint ownership arrangements, business interests, registered accounts, real estate, and other assets can also affect how wealth is transferred.
The Government of Canada explains that estate law, including wills and probate, is largely governed by the province or territory where the individual lived. Its guidance also highlights the role of wills, executors, estate administration, and tax obligations. Government of Canada guidance on estates and wills
This makes coordination particularly important. A will should not necessarily be considered in isolation from the rest of a person’s financial arrangements.
Understand What You Own
Before deciding how wealth should eventually be transferred, it helps to understand what actually makes up the estate.
For some people, the picture may be relatively straightforward: a home, savings, investments, and personal belongings.
For others, it can be considerably more complex.
Assets may include investment portfolios, rental properties, corporations, partnership interests, insurance policies, registered accounts, private investments, or interests in family businesses.
The ownership structure can matter just as much as the value of the asset.
For example, an asset owned personally may be treated differently from an interest held through a corporation or another structure. Similarly, an account with a named beneficiary may follow a different transfer process from an asset that forms part of the estate.
Exponent Investment Management works with professionals, business owners, and families on wealth management and financial planning, illustrating why estate considerations can be incorporated into a broader review of a family’s financial position.
The purpose is not to make every estate arrangement complicated. It is to make sure the plan reflects what the individual actually owns and how those assets are intended to support family and legacy objectives.
Consider Beneficiaries and Family Goals
Estate planning is ultimately about people as much as assets.
A family may have straightforward inheritance goals, while another may need to consider different financial needs among children, charitable intentions, a surviving spouse, or other beneficiaries.
There may also be situations where equal treatment does not necessarily mean identical distributions. One child might already be financially independent, for example, while another may have different circumstances.
Business owners can face additional questions when family members are involved in a company.
Who should eventually receive ownership? Should ownership and management be treated as separate questions? What happens if some family members want to continue the business while others do not?
These decisions can require legal, tax, and financial expertise. The important point is to identify the goals early enough that the appropriate professionals have time to coordinate them.
Think About Taxes and Business Assets
Tax considerations can be an important part of estate planning in Canada.
When a person dies, certain assets can create tax consequences, and the estate may have responsibilities that need to be addressed before assets are distributed.
The Canada Revenue Agency explains that a deceased person’s legal representative may need to file a final tax return and, depending on the circumstances, additional returns for the estate. Certain property and investments may also have tax implications at death.
This is one reason estate planning should not simply focus on who receives an asset. It can also be important to consider the financial consequences associated with transferring or disposing of that asset.
Business owners may have additional considerations involving corporate shares, partnership interests, commercial property, or succession arrangements.
A business can represent a substantial portion of a family’s wealth, so succession planning and estate planning may overlap. The appropriate structure depends on the individual’s circumstances and should be developed with qualified legal and tax professionals.
Coordinate Financial and Legal Planning
Estate planning often involves several different areas of expertise.
A lawyer may handle wills, powers of attorney, trusts, ownership arrangements, and other legal documents. An accountant or tax professional can address tax consequences and reporting obligations. A financial professional can help connect investment assets, insurance, retirement objectives, liquidity needs, and family goals.
The roles are different, but the decisions can be connected.
For example, changing an investment strategy could affect the assets ultimately available to beneficiaries. A change in insurance coverage could alter the amount of liquidity available to an estate. A business succession decision could affect retirement income as well as the eventual transfer of wealth.
An integrated financial planning approach can help ensure these decisions are considered together rather than being developed independently.
This does not mean one professional should replace the others. Instead, coordinated planning can help each specialist understand the broader objectives.
Review the Plan Over Time
Estate plans can become outdated even when the original documents remain legally valid.
Families change. Assets are bought and sold. Businesses grow or change ownership. People move between provinces or territories. Relationships change. Beneficiaries may have different circumstances years later.
For these reasons, estate planning is something that can benefit from periodic review.
Major life events can be natural opportunities to revisit the plan. These might include marriage, divorce, the birth of a child, a significant inheritance, the purchase or sale of a business, a major change in wealth, or a move to another jurisdiction.
Investment and financial accounts should also be reviewed to ensure beneficiary designations and ownership information remain consistent with the broader intentions of the estate plan.
A document that says one thing while an account designation says another can create unnecessary complexity for families.
Connecting Estate Planning With Wealth Management
Estate planning becomes more meaningful when it is considered alongside the rest of a person’s financial life.
Investment decisions affect the assets available for future beneficiaries. Retirement planning influences how much wealth may need to remain available during a person’s lifetime. Insurance can provide liquidity. Business succession can determine how a major asset is transferred. Tax planning can affect the amount ultimately available to the estate.
Integrated financial planning can provide a framework for bringing these considerations into the same broader conversation while allowing lawyers and tax professionals to address their respective areas of expertise.
The goal is not to predict every future circumstance or guarantee a particular outcome. It is to establish a structure that reflects current intentions and can be adjusted when those intentions or circumstances change.
Building a More Complete Wealth Transfer Plan
Estate planning is most effective when it reflects the full financial picture rather than focusing only on a will.
Understanding assets, reviewing beneficiary arrangements, considering family goals, identifying tax implications, preparing for business succession, and coordinating with qualified professionals can all contribute to a more complete approach to wealth transfer.
For families with increasingly complex financial lives, the process can also provide an opportunity to connect today’s financial decisions with longer-term goals.
A thoughtful estate plan is ultimately not just about what happens to wealth after death. It is about making sure the financial, legal, and family decisions made today remain aligned with the legacy a person intends to leave.
